Credit Settlement Risk in the USA: What You Need to Know Before Settling Your Debt
Credit settlement can seem like an attractive option for Americans struggling with overwhelming credit card debt and other unsecured debts. The possibility of paying less than the total amount owed can provide financial relief.
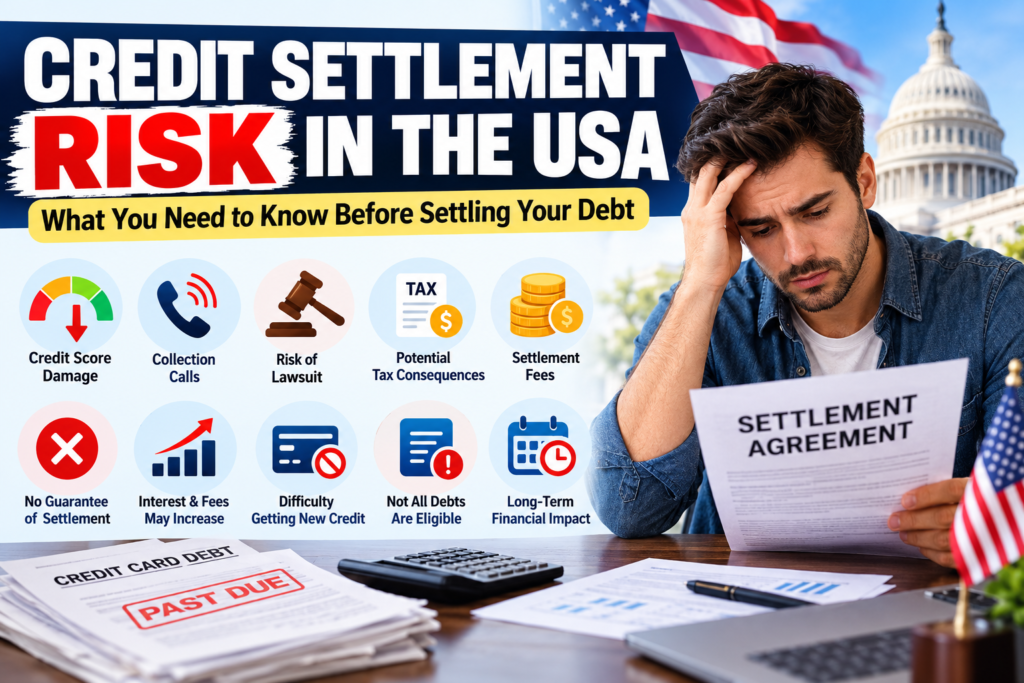
However, credit settlement risk in the USA is an important consideration. Debt settlement can negatively affect your credit score, increase collection activity, create potential tax consequences, and in some situations expose you to the risk of a lawsuit.
Before enrolling in a debt settlement program, it is important to understand both the potential benefits and the risks.
What Is Credit Settlement?
Credit settlement, often referred to as debt settlement, is a process in which a creditor agrees to accept less than the full amount a consumer owes.
For example, imagine that you have $20,000 in eligible unsecured debt. A settlement agreement might allow you to resolve the debt for a lower amount, such as $12,000, depending on negotiations and the creditor’s willingness to settle.
The remaining balance may be forgiven under the settlement agreement, but forgiveness does not necessarily mean there are no financial consequences.
Debt settlement is generally associated with unsecured debts such as:
- Credit card debt
- Certain personal loans
- Medical bills
- Some private student loans
- Other qualifying unsecured debts
Secured debts, such as mortgages and auto loans, generally work differently because the creditor has an interest in collateral.
What Are the Biggest Credit Settlement Risks in the USA?
1. Credit Score Damage
One of the most significant risks of debt settlement is potential damage to your credit history.
Some settlement programs may involve stopping payments to creditors while funds are accumulated for negotiations. Missing payments can result in late-payment reporting to the credit bureaus.
Because payment history is an important part of credit scoring, repeated missed payments can cause a substantial decline in your credit score.
A settled account can also remain part of your credit history and may make future borrowing more difficult.
2. Increased Collection Activity
Entering a debt settlement program does not automatically prevent creditors or debt collectors from attempting to collect the debt.
You may continue receiving:
- Collection calls
- Letters
- Payment notices
- Settlement offers
- Collection-related communications
The possibility of collection activity is something consumers should understand before entering a settlement program.
3. Risk of a Debt Collection Lawsuit
Another major debt settlement risk is the possibility of legal action.
If you stop making payments, a creditor may decide to pursue collection through the legal system.
A lawsuit can result in additional expenses and stress. If a creditor obtains a judgment, additional collection remedies may be available under applicable state law.
For this reason, consumers should never assume that a debt settlement company can prevent a creditor from suing.
4. Potential Tax Consequences
Debt forgiveness may have tax implications.
In certain circumstances, the IRS may consider canceled or forgiven debt to be taxable income. However, exceptions and exclusions can apply depending on the individual’s circumstances.
For example, if a creditor agrees to forgive $8,000 of debt, the consumer should not automatically assume that the entire amount is completely tax-free.
Anyone considering debt settlement should understand the potential tax consequences and consider consulting a qualified tax professional.
5. Debt Settlement Fees
Debt settlement companies typically charge fees for their services.
These fees can reduce the amount of money ultimately available to resolve your debt.
Before signing an agreement, ask:
- How are fees calculated?
- When are fees charged?
- Are fees based on enrolled debt or settled debt?
- Are there additional account fees?
- What happens if the company cannot settle a particular debt?
Understanding the fee structure can help you calculate the actual cost of the program.
6. No Guarantee of Successful Settlement
One of the most important things consumers should understand is that creditors do not have to accept a settlement offer.
A debt settlement company may negotiate on your behalf, but the creditor ultimately decides whether to accept the proposed settlement.
Therefore, promises that your debt will definitely be reduced by a specific percentage should be treated cautiously.
7. Your Debt Balance Could Increase
When payments are missed, interest, late charges, and other fees may continue to accumulate depending on the terms of the account.
As a result, your outstanding balance could increase while you are waiting for settlement negotiations.
This means that the amount eventually negotiated may not be based on the balance you originally owed.
8. Difficulty Getting New Credit
Debt settlement can affect your ability to obtain new credit.
Potential lenders may review your credit history when you apply for:
- Credit cards
- Mortgages
- Auto loans
- Personal loans
- Business financing
A damaged credit profile could result in higher interest rates, lower credit limits, or difficulty qualifying for certain financial products.
9. Not All Debts Are Suitable for Settlement
Debt settlement is generally more relevant to unsecured debt.
A consumer with a combination of credit card debt, an auto loan, and a mortgage should understand that these debts have different structures and risks.
Before choosing debt settlement, consumers should identify exactly which debts are eligible and understand what could happen to each account.
10. Long-Term Financial Consequences
The consequences of debt settlement can extend beyond the settlement itself.
Even after resolving the debt, rebuilding credit may take time.
Consumers may need to focus on:
- Making every payment on time
- Reducing credit utilization
- Building an emergency fund
- Avoiding unnecessary new debt
- Monitoring their credit reports
- Establishing a sustainable monthly budget
Debt settlement may resolve an immediate debt problem, but long-term financial habits are still important.
How Does Debt Settlement Affect Your Credit Score?
Credit settlement can affect your credit in several ways.
If you miss payments before a settlement is reached, those late payments may appear on your credit reports.
Your credit utilization may also remain high while balances are outstanding.
After settlement, the account may be reported as settled rather than paid in full, depending on how the creditor reports the account.
The exact impact varies from person to person because credit scores depend on multiple factors.
Credit Settlement vs. Debt Consolidation
Debt settlement and debt consolidation are not the same thing.
Debt settlement attempts to negotiate a lower amount to resolve eligible debt.
Debt consolidation generally combines multiple debts into one new loan or payment arrangement.
Debt consolidation may be more suitable for some consumers who have sufficient credit and income to qualify for favorable terms.
However, consolidation does not automatically reduce the principal amount owed.
Credit Settlement vs. Credit Counseling
Nonprofit credit counseling can be another option for consumers struggling with debt.
A credit counselor may help you review your budget and determine whether a structured repayment plan could work.
Depending on your situation, a debt management plan may reduce interest rates or simplify payments, although it generally does not work in the same way as debt settlement.
How to Evaluate a Debt Settlement Company
If you are considering professional debt settlement services, research the company carefully.
Look for clear information about:
- Fees
- Contract terms
- Cancellation policies
- Creditor communication
- Settlement timelines
- Potential risks
- Consumer complaints
- Regulatory history
Be particularly cautious about companies making unrealistic guarantees or claiming that they can eliminate your debt without consequences.
Questions to Ask Before Signing Up
Before enrolling in a debt settlement program, ask:
- How much will the program cost?
- When will I be charged?
- Which debts can be included?
- What happens if a creditor refuses the settlement?
- What happens if I leave the program?
- Could my creditors continue collection activity?
- Could I be sued?
- What could happen to my credit score?
- Could forgiven debt create tax consequences?
- Are there alternatives that may be better for my situation?
How to Reduce Credit Settlement Risk
There is no way to eliminate every risk, but consumers can make more informed decisions.
Review Your Complete Financial Situation
Calculate your total debt, monthly income, expenses, savings, and available cash before choosing a strategy.
Understand the Total Cost
Do not focus only on the advertised settlement amount. Consider fees, interest, potential taxes, and other costs.
Get Independent Advice
Consider speaking with a qualified financial professional, nonprofit credit counselor, attorney, or tax professional when appropriate.
Read Everything Before Signing
Never sign a settlement agreement without understanding its fees, obligations, cancellation terms, and potential consequences.
Is Credit Settlement Worth It?
For some consumers facing serious unsecured debt, settlement may be one possible strategy.
However, it is not a universal solution.
The potential benefit of reducing the amount owed needs to be weighed against possible credit damage, collection activity, lawsuits, fees, tax consequences, and difficulty obtaining future credit.
The best approach depends on your financial circumstances and the type of debt you have.
Final Thoughts
Understanding credit settlement risk in the USA is essential before making a decision about debt relief.
Debt settlement may potentially reduce the amount needed to resolve certain unsecured debts, but consumers should understand that the process can involve significant risks.
Before enrolling in a program, compare debt settlement with alternatives such as credit counseling, debt consolidation, negotiating directly with creditors, and other options that may be appropriate for your circumstances.
The goal should not simply be to reduce today’s debt balance. It should be to find a solution that helps you achieve long-term financial stability while minimizing unnecessary financial and credit damage.
Disclaimer: This article is for educational and informational purposes only. It is not legal, tax, credit, or financial advice. Debt collection, credit reporting, bankruptcy, and tax rules can vary based on individual circumstances and applicable federal and state laws. Consider consulting an appropriately qualified professional before making a major financial decision.
Credit Settlement, Credit Settlement Risk, Debt Settlement USA, Debt Relief, Credit Card Debt, Debt Settlement Risks, Credit Score, Debt Management, Financial Planning, Personal Finance, Debt Relief USA
10 Frequently Asked Questions About Credit Settlement Risk
1. What is credit settlement?
Credit settlement is a process where a creditor agrees to accept less than the total amount owed to resolve a debt.
2. Does credit settlement hurt your credit score?
It can. Missed payments associated with the settlement process may negatively affect your credit history, and a settled account may be reported differently from an account paid in full.
3. Can you be sued after entering debt settlement?
Yes. A creditor may pursue legal action depending on the circumstances. Enrolling in a settlement program does not automatically prevent a lawsuit.
4. Is forgiven debt taxable in the USA?
In some circumstances, canceled or forgiven debt may be treated as taxable income. However, exceptions and exclusions may apply.
5. Does debt settlement eliminate all of your debt?
Not necessarily. Settlement generally applies only to debts that creditors agree to resolve, and not every creditor will accept a settlement offer.
6. How much can debt settlement reduce your debt?
There is no guaranteed percentage. The amount depends on factors such as the creditor, account status, debt amount, consumer circumstances, and negotiations.
7. What debts can usually be settled?
Debt settlement is commonly associated with certain unsecured debts, including credit card balances and some personal or medical debts. Eligibility varies.
8. Is debt consolidation better than debt settlement?
It depends on your circumstances. Debt consolidation combines debts, while settlement seeks to negotiate a lower payoff amount. Each option has different requirements, costs, and risks.
9. How long does it take to rebuild credit after debt settlement?
There is no fixed timeline. Rebuilding credit depends on factors such as payment history, outstanding balances, credit utilization, and future financial behavior.
10. What should I consider before choosing debt settlement?
Consider the potential impact on your credit, collection activity, lawsuit risk, fees, tax consequences, settlement success rate, and alternative debt-relief options before making a decision.