
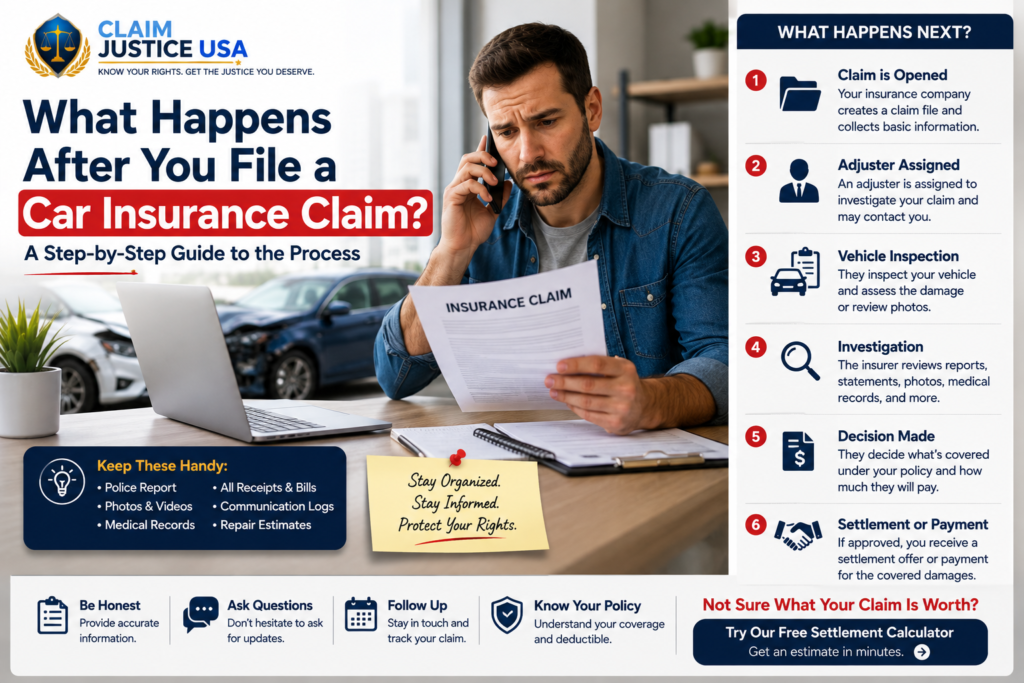
What Happens After You File a Car Insurance Claim?
By Claim Justice USA
You finally made the call.
You reported the accident to your insurance company, gave them the basic details, and submitted the information you had.
Then you hung up the phone.
And suddenly you thought:
“Okay… what happens now?”
If you’ve never filed an insurance claim before, the process can feel confusing.
You may wonder when someone will inspect your car, when you’ll hear from an adjuster, whether your medical bills are covered, and how long everything is going to take.
And if you were injured, there’s another question sitting in the back of your mind:
“When do I actually find out what my claim is worth?”
Let’s walk through what usually happens after an auto insurance claim is reported.
Step 1: The Insurance Company Opens Your Claim
Once you report the accident, the insurer generally creates a claim file.
You’ll usually be asked for information about:
- When the accident happened
- Where it happened
- What happened
- Vehicles involved
- Other driver’s information
- Police report information
- Damage to your vehicle
- Injuries, if any
- Witnesses
- Photos or videos
The National Association of Insurance Commissioners (NAIC) recommends collecting accident information, keeping records of conversations, and contacting your insurer promptly according to your policy requirements.
The more organized you are at this stage, the easier the process can become.
Step 2: An Insurance Adjuster May Contact You
This is usually when the claim starts feeling “real.”
An adjuster may be assigned to your claim.
Their job is to investigate the loss and help determine what the insurance company will pay under the applicable policy.
The adjuster may ask questions about the accident.
They may ask to inspect your vehicle.
They may request documents.
They may ask about your injuries.
Don’t be surprised by the questions.
But don’t guess when you don’t know an answer.
If you don’t remember something, simply say that you don’t remember.
Accurate information is more important than sounding certain.
Step 3: Your Car Gets Inspected
If your vehicle was damaged, the insurer may arrange an inspection or request photographs.
The adjuster may determine:
- What parts are damaged
- Whether the damage appears related to the accident
- Whether repairs are practical
- The estimated repair cost
- Whether the vehicle may be considered a total loss
Your policy matters here.
Different types of coverage can apply in different situations. NAIC explains that collision coverage generally addresses damage caused by a collision, while comprehensive coverage addresses certain non-collision losses such as theft, weather damage, fire, or animal impact.
So don’t assume that every type of damage is automatically covered.
Step 4: The Insurance Company Reviews the Evidence
Now the investigation begins.
The insurer may review:
Police reports
Photos
Witness information
Vehicle damage
Statements from the drivers
Medical information
Insurance policy terms
Other relevant evidence
This is one reason taking photographs immediately after the accident can be so valuable.
A photograph can sometimes show details that are difficult to explain weeks later.
Step 5: You May Be Asked About Your Injuries
If you were hurt, the insurance company may ask about your medical treatment.
You may be asked:
- Where did you receive treatment?
- When did symptoms begin?
- What treatment have you received?
- Are you still treating?
- Have you had similar problems before?
- Have you missed work?
Answer truthfully.
Don’t exaggerate.
But don’t minimize your injuries either.
If your neck hurts, say your neck hurts.
If you’re having trouble sleeping, explain that honestly to your medical provider.
Your medical records can become important evidence in an injury claim.
Here’s Where Things Can Get Complicated
Let’s go back to our fictional driver, Mike.
Remember him?
He was rear-ended while waiting at a traffic light.
At first, he thought the accident wasn’t too serious.
Then his neck pain got worse.
Now imagine that two months later, his insurance claim contains:
- $12,000 in medical expenses
- $3,500 in lost wages
- $7,000 in vehicle damage
- Ongoing physical therapy
- Continuing neck pain
The insurance company might look at the claim and see one set of numbers.
Mike looks at the claim and sees something different.
He sees the days he couldn’t work.
The nights he couldn’t sleep.
The appointments he had to attend.
The things he stopped doing.
That’s why an insurance claim isn’t always as simple as:
“Here are my bills. Please send me a check.”
Step 6: The Insurance Company Makes a Decision
After investigating the claim, the insurer may approve payment, partially approve it, dispute parts of it, or deny the claim depending on the circumstances and policy.
If the insurer agrees that a covered loss occurred, the payment process begins according to the applicable coverage and policy terms.
If there is a disagreement, ask questions.
The NAIC recommends asking the adjuster for a written explanation of decisions and says consumers who disagree with claim handling should try to resolve the issue with the insurer; state insurance departments may also provide consumer assistance.
What If You Think the Insurance Company Is Wrong?
Don’t immediately assume you have no options.
First, find out why.
Maybe the insurer says some damage wasn’t caused by the accident.
Maybe they believe another driver was responsible.
Maybe they don’t have all your medical records.
Maybe they calculated your vehicle’s value differently than you expected.
Ask for the explanation in writing.
Then compare their position with your documentation.
This turns an emotional argument into a factual discussion.
Keep Your Own Claim File
Here’s something simple that can make life easier.
Create a folder called:
“Car Accident Claim”
Put everything inside.
For example:
01 — Police Report
02 — Insurance Documents
03 — Medical Records
04 — Medical Bills
05 — Lost Income
06 — Vehicle Damage
07 — Photos & Videos
08 — Insurance Communications
09 — Settlement Offers
It sounds simple.
But when six months have passed and you have dozens of documents, you’ll be glad everything is organized.
How Long Does an Insurance Claim Take?
This is one of the most common questions.
Unfortunately, there isn’t one answer for every claim.
A simple property-damage claim may move relatively quickly.
A serious injury claim can take much longer.
Why?
Because the insurer may need to investigate liability, review medical treatment, evaluate damages, and determine what the applicable policy covers.
Some states also have specific rules regarding claim handling and settlement timing.
NAIC notes that claim timelines can vary, especially when an insurer needs additional investigation.
So if someone tells you:
“Your claim should definitely settle in exactly 30 days.”
Be careful.
Your situation may be completely different.
Don’t Confuse a Car Repair Payment With an Injury Settlement
This is an important distinction.
Suppose your car needs $8,000 worth of repairs.
The insurance company agrees to pay for the covered vehicle damage.
That doesn’t necessarily mean your injury claim has been resolved.
Property damage and bodily injury can involve different issues and different coverage.
If you were injured, make sure you understand exactly what you’re agreeing to before signing a settlement or release.
What If the Insurance Company Makes a Settlement Offer?
This is where many people get nervous.
You receive a letter:
Settlement Offer: $18,000
Your first reaction might be:
“Should I take it?”
Before deciding, look at the bigger picture.
Have you finished treatment?
Do you know your total medical expenses?
Have you documented lost income?
Do you expect future treatment?
Does the settlement release your remaining claims?
Is there a dispute over who caused the accident?
If the injury is significant, speaking with a qualified attorney licensed in the applicable state may be worthwhile before accepting a final settlement.
What About a Low Settlement Offer?
Suppose your documented losses are substantial, but the insurer offers considerably less than you expected.
Don’t just respond:
“I want more.”
Instead, ask:
“Can you provide a written explanation of how this amount was calculated?”
Then review the details.
Maybe the insurer didn’t have a medical bill.
Maybe they disagree about the severity of your injury.
Maybe they are disputing liability.
Maybe they have a different valuation of your vehicle.
Understanding the reason behind the offer gives you something specific to respond to.
For additional background, the NAIC’s consumer guidance explains that you don’t have to agree to a settlement you believe is unfair and recommends asking questions and seeking assistance when disagreements cannot be resolved.
What If You Don’t Know What Your Claim Is Worth?
That’s completely understandable.
Most people aren’t insurance experts.
You can start by calculating your documented losses.
For example:
| Loss | Amount |
|---|---|
| Medical bills | $15,000 |
| Lost wages | $4,000 |
| Vehicle damage | $8,000 |
| Other documented expenses | $1,000 |
| Total | $28,000 |
That $28,000 isn’t automatically your settlement value.
Your potential claim can also depend on injury severity, pain and suffering, future treatment, liability, insurance limits, applicable state law and other factors.
But organizing your numbers gives you a much better starting point.
Use a Car Accident Settlement Calculator
This is where an online calculator can be useful.
The Claim Justice USA Car Accident Settlement Calculator can help you organize the basic numbers and produce an initial estimate.
You can consider things such as:
- Medical expenses
- Lost income
- Property damage
- Injury severity
- Other losses
Calculate Your Potential Settlement — Free
No signup required.
Just remember:
A calculator is an estimate, not a guarantee.
No online tool can know every detail of your claim.
What Should You Do While Your Claim Is Pending?
Don’t just sit around waiting for the insurance company.
Keep taking care of yourself.
Keep your medical appointments.
If your doctor recommends treatment, follow the medical advice appropriate for your condition.
Keep your documents.
Save every relevant bill and record.
Track your expenses.
Even small expenses can add up.
Keep your employer records.
Document time missed from work.
Save insurance communications.
Keep emails, letters and notes from phone calls.
Keep documenting your recovery.
If your symptoms change, keep a simple record and discuss medical concerns with your healthcare provider.
One More Thing: Read Before You Sign
This sounds obvious.
But when you’re exhausted and the insurance company finally offers money, it can be tempting to sign immediately.
Don’t sign something you don’t understand.
Read it.
Ask what the document does.
Understand whether it releases your claim.
If you’re unsure about the legal consequences, consider getting advice from a qualified attorney before signing.
The Insurance Claim Process Isn’t Just About a Check
At first, you may think:
Accident → Insurance Claim → Check
Real life is usually more complicated.
It’s more like:
Accident
↓
Report the claim
↓
Investigation
↓
Evidence and documentation
↓
Damage and injury evaluation
↓
Negotiation or decision
↓
Settlement, payment, dispute, or other resolution
Knowing this can make the process feel less mysterious.
You don’t have to know everything on Day One.
You just need to keep good records and understand what is happening at each stage.
Final Thoughts
If you’ve just filed a car insurance claim, waiting can be frustrating.
You may be worried about your car.
You may be worried about medical bills.
You may be worried about missing work.
And you may have no idea whether the insurance company’s eventual offer will be fair.
The best thing you can do is stay organized.
Document everything.
Keep your medical records.
Track your financial losses.
Ask questions.
Read settlement documents carefully.
And remember that the first number an insurance company gives you isn’t necessarily the end of the conversation.
Your claim has a story behind it.
Make sure that story is supported by good evidence.
Important Disclaimer
This article is for general informational and educational purposes only and is not legal advice. Insurance laws, deadlines, coverage rules and personal injury laws vary by state. The examples in this article are hypothetical and do not predict the value or outcome of any individual claim. Claim Justice USA does not guarantee any settlement amount. For advice about your specific circumstances, consult a qualified attorney licensed in the applicable state.
Helpful Resources
- National Association of Insurance Commissioners — Auto Insurance
- NAIC — What You Should Know About Filing an Auto Claim
- NAIC — What Does Auto Insurance Cover?
